
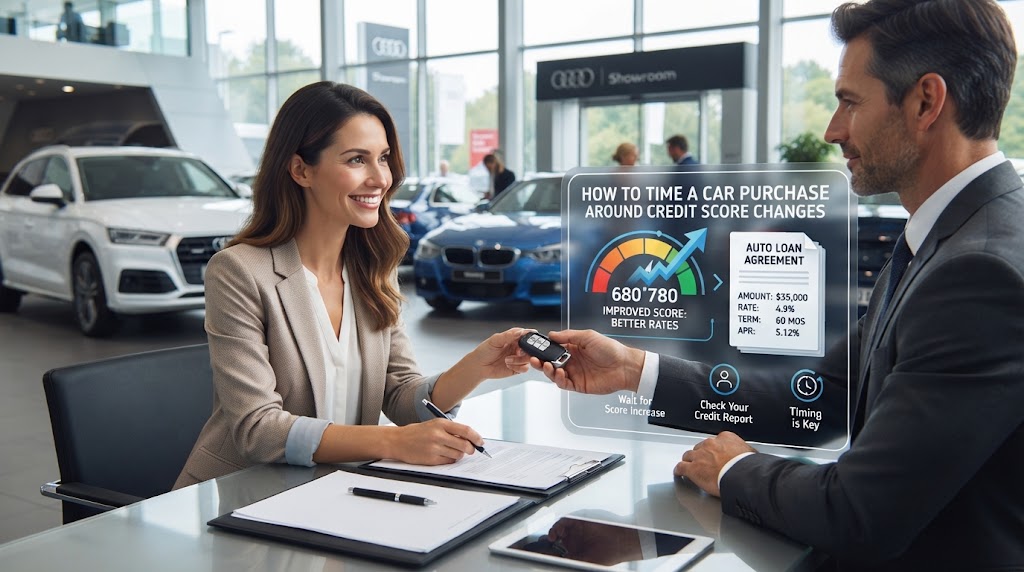
Here’s a number that stings: the difference between a 680 and a 760 credit score on a $35,000 car loan is roughly $4,200 in extra interest over five years. That’s not a rounding error, that’s a used Honda Civic. Most buyers don’t realize their score isn’t a static number they get handed on a Tuesday. It moves monthly, sometimes weekly, and the exact week you apply for financing can be worth more than the haggling you do on the hood.
Here’s what we’ll do: show you when to pull your score, when to actually walk into a dealership, and the 62-day rule that lets you shop multiple lenders without wrecking your credit. You’ll leave with a timing plan, not vague advice about “improving your score first.”
What’s Actually Inside Your Score That Changes Monthly?
Your credit score is a snapshot of your credit report at a specific moment, and that snapshot changes as your creditors report to the bureaus. Most lenders report your balance, payment history, and credit utilization once per month, typically on your statement closing date. So if your credit card balance was $8,000 on the 3rd but you paid it down to $1,000 by the 20th, your score might still reflect the higher number for weeks.
This lag matters more than you’d think. The Consumer Financial Protection Bureau found that consumers who regularly check their credit reports via the annual free disclosure are more likely to catch errors that drag down their scores. A single mistaken late payment can cost you 100 points, points that determine whether you qualify for the competitive auto loan rates you’d otherwise get.
Your utilization ratio, the amount you owe compared to your limits, is the second-biggest factor in your score after payment history. It’s also the most volatile. If you pay down a card before your statement closing date, your utilization drops, and your score often responds within a month. That’s a lever you can pull deliberately before you buy a car.
Why the Month Before You Buy Is the Most Important Month
Lenders don’t care what your score was last year or last quarter. They pull your score at the moment you apply. So the entire game is about engineering your score to peak right when you submit that application, then signing before anything drags it back down.
Here’s the sequence that works in practice. Thirty to sixty days before you plan to buy, check your credit report from all three bureaus at AnnualCreditReport.com. Dispute anything that looks wrong. Then, pay down revolving balances so your utilization sits under 30%, ideally under 10% if you can manage it. The credit bureaus generally update scores once new balances are reported, so this gives you a full reporting cycle to see the improvement.
Then wait for your statement to close, and pull your FICO score, not the VantageScore that free apps often show you. Automotive lenders overwhelmingly use FICO Auto Scores, which weight your history with installment loans a bit differently. Experian’s 2024 State of the Automotive Finance Market report showed that the average newly financed new car carried an APR of 7.1%, but that average hides a massive spread: top-tier borrowers got rates near 5%, while subprime borrowers paid double digits. The score you present to the lender decides which side of that spread you land on.
How Many Points Does Hard Pulling Your Credit Actually Cost?
Here’s where most buyers panic and freeze. They worry that checking rates at a few banks will tank their score, so they take whatever the dealer’s first offer gives them. That’s backwards.
A hard inquiry typically costs five points or fewer, and it only affects your score for about 12 months, with the impact fading after six. More importantly, the scoring models treat multiple auto loan inquiries within a short window as one inquiry. FICO gives you a 45-day window, newer models stretch it to 45 days from the first application, but both effectively allow you to shop four or five lenders without repeat penalties. After that window closes, each new application counts separately.
So the move is to do all your rate shopping in one focused week, then pick the best offer. Waiting two months between applications spreads the damage out and makes it worse.
The 62-Day Rule That Protects Your Score While You Shop
This is the single most valuable timing hack in this entire article. When you take out a car loan, creditors don’t report your new account to the credit bureaus immediately. They report it on your first billing cycle, which is typically 30 to 45 days after you sign. But the bureaus take another 15 to 30 days to process and display that new account on your report.
Net effect: you have roughly 60 days, usually closer to 62, after signing before the new loan shows up as a new account on your credit file. During that window, your score temporarily looks better than it does after the loan posts, because the new debt isn’t counted yet while the old balances are still paid down.
Why does that matter? If you’re planning to do anything else credit-sensitive within two months of buying a car, like refinancing a student loan, moving to a new apartment with a credit check, or applying for a rewards card with a big sign-up bonus, do it before you sign the car contract.
The Federal Trade Commission’s guidance on credit reports makes clear that lenders and landlords see the same data you do, just at different update cycles, and a new auto loan typically drops your score once it posts because it adds a new account, a new monthly obligation, and occasionally a small utilization jump. Timing matters precisely because the data is stale in your favor for those 62 days.
Step-by-Step: The 6-Week Car Buying Calendar
Here’s a concrete plan, not a vague “get your finances in order” suggestion. Print this out.
- Week 1: Pull all three credit reports from AnnualCreditReport.com. Dispute errors immediately. Most disputes resolve within 30 days.
- Week 2: Pay down credit card balances so utilization moves below 30%. Aim for 10% if possible. Wait for your statement to close.
- Week 3: Check your FICO score from a credit card issuer or a paid service. Confirm the utilization drop registered.
- Week 4: Apply for preapproval with two or three lenders in the same week. This counts as one inquiry cluster. Compare the offers side by side.
- Week 5: Shop the actual car using your preapproval as leverage. Let the dealer try to beat it, but don’t let them run your credit again.
- Week 6: Sign the paperwork. Then, within the next month, complete any other credit applications you’ve been holding off on before the loan posts to your report.
A Realistic Look at Rate Ranges (Before You Obsess Over 2 Points)
Let’s put real numbers on a table so you can see what timing is actually worth to you.
| FICO Score Band | Average New Car APR (2024) | Interest Paid on $35k, 60-Month Loan
|
|---|---|---|
| 781 to 850 | 5.1% | $4,723 |
| 661 to 780 | 6.9% | $6,486 |
| 601 to 660 | 10.1% | $9,688 |
| 501 to 600 | 15.3% | $15,190 |
Those figures come from Experian’s 2024 automotive finance data, and they show two things. First, the gap between a 720 and a 700 is not the same as the gap between a 650 and a 630. The scoring bands have cliffs, and crossing a cliff point saves you thousands. Second, waiting one extra month to push your score from 650 to 670 is almost always worth more than the depreciation you’ll eat on that same car in that same month.
My honest take: most people overthink the dealer negotiation and underthink the credit timing. You can squeeze a dealer for $1,000 off the price, or you can squeeze your credit file for a rate that saves you $3,000. The second one has a bigger payoff and it’s entirely within your control. Do the boring work on your score first.
What If You Need the Car Right Now?
Sometimes the timing doesn’t work. Your transmission dies, your commute is 45 minutes each way, and the “wait a month and improve your score” advice feels like a luxury you don’t have. Fair enough.
In that case, take the best rate you can get today, then refinance in six to twelve months once your score has recovered and you’ve built a clean payment history on the new loan. The cash flow hit from a slightly higher rate for a year is far smaller than the cost of buying a car with no bargain equity or settling for a beater that fails you in six months. Refinancing costs a small fee and a hard inquiry, which barely moves your score by then.
One thing to remember though: don’t let a dealership’s “sign now, we’ll handle your credit later” pitch push you out of the shopping window. The FICO inquiry window gives you room to compare, and the 62-day posting lag gives you room to breathe. Use both. They’re the two most underrated tools in a car buyer’s arsenal, and most people never know they exist.
What’s your score today, and what does your current rate offer look like? That answer tells you whether your timing is good or whether you should hit pause for one more month. Sometimes the cheapest purchase you’ll ever make is the one you delay.