
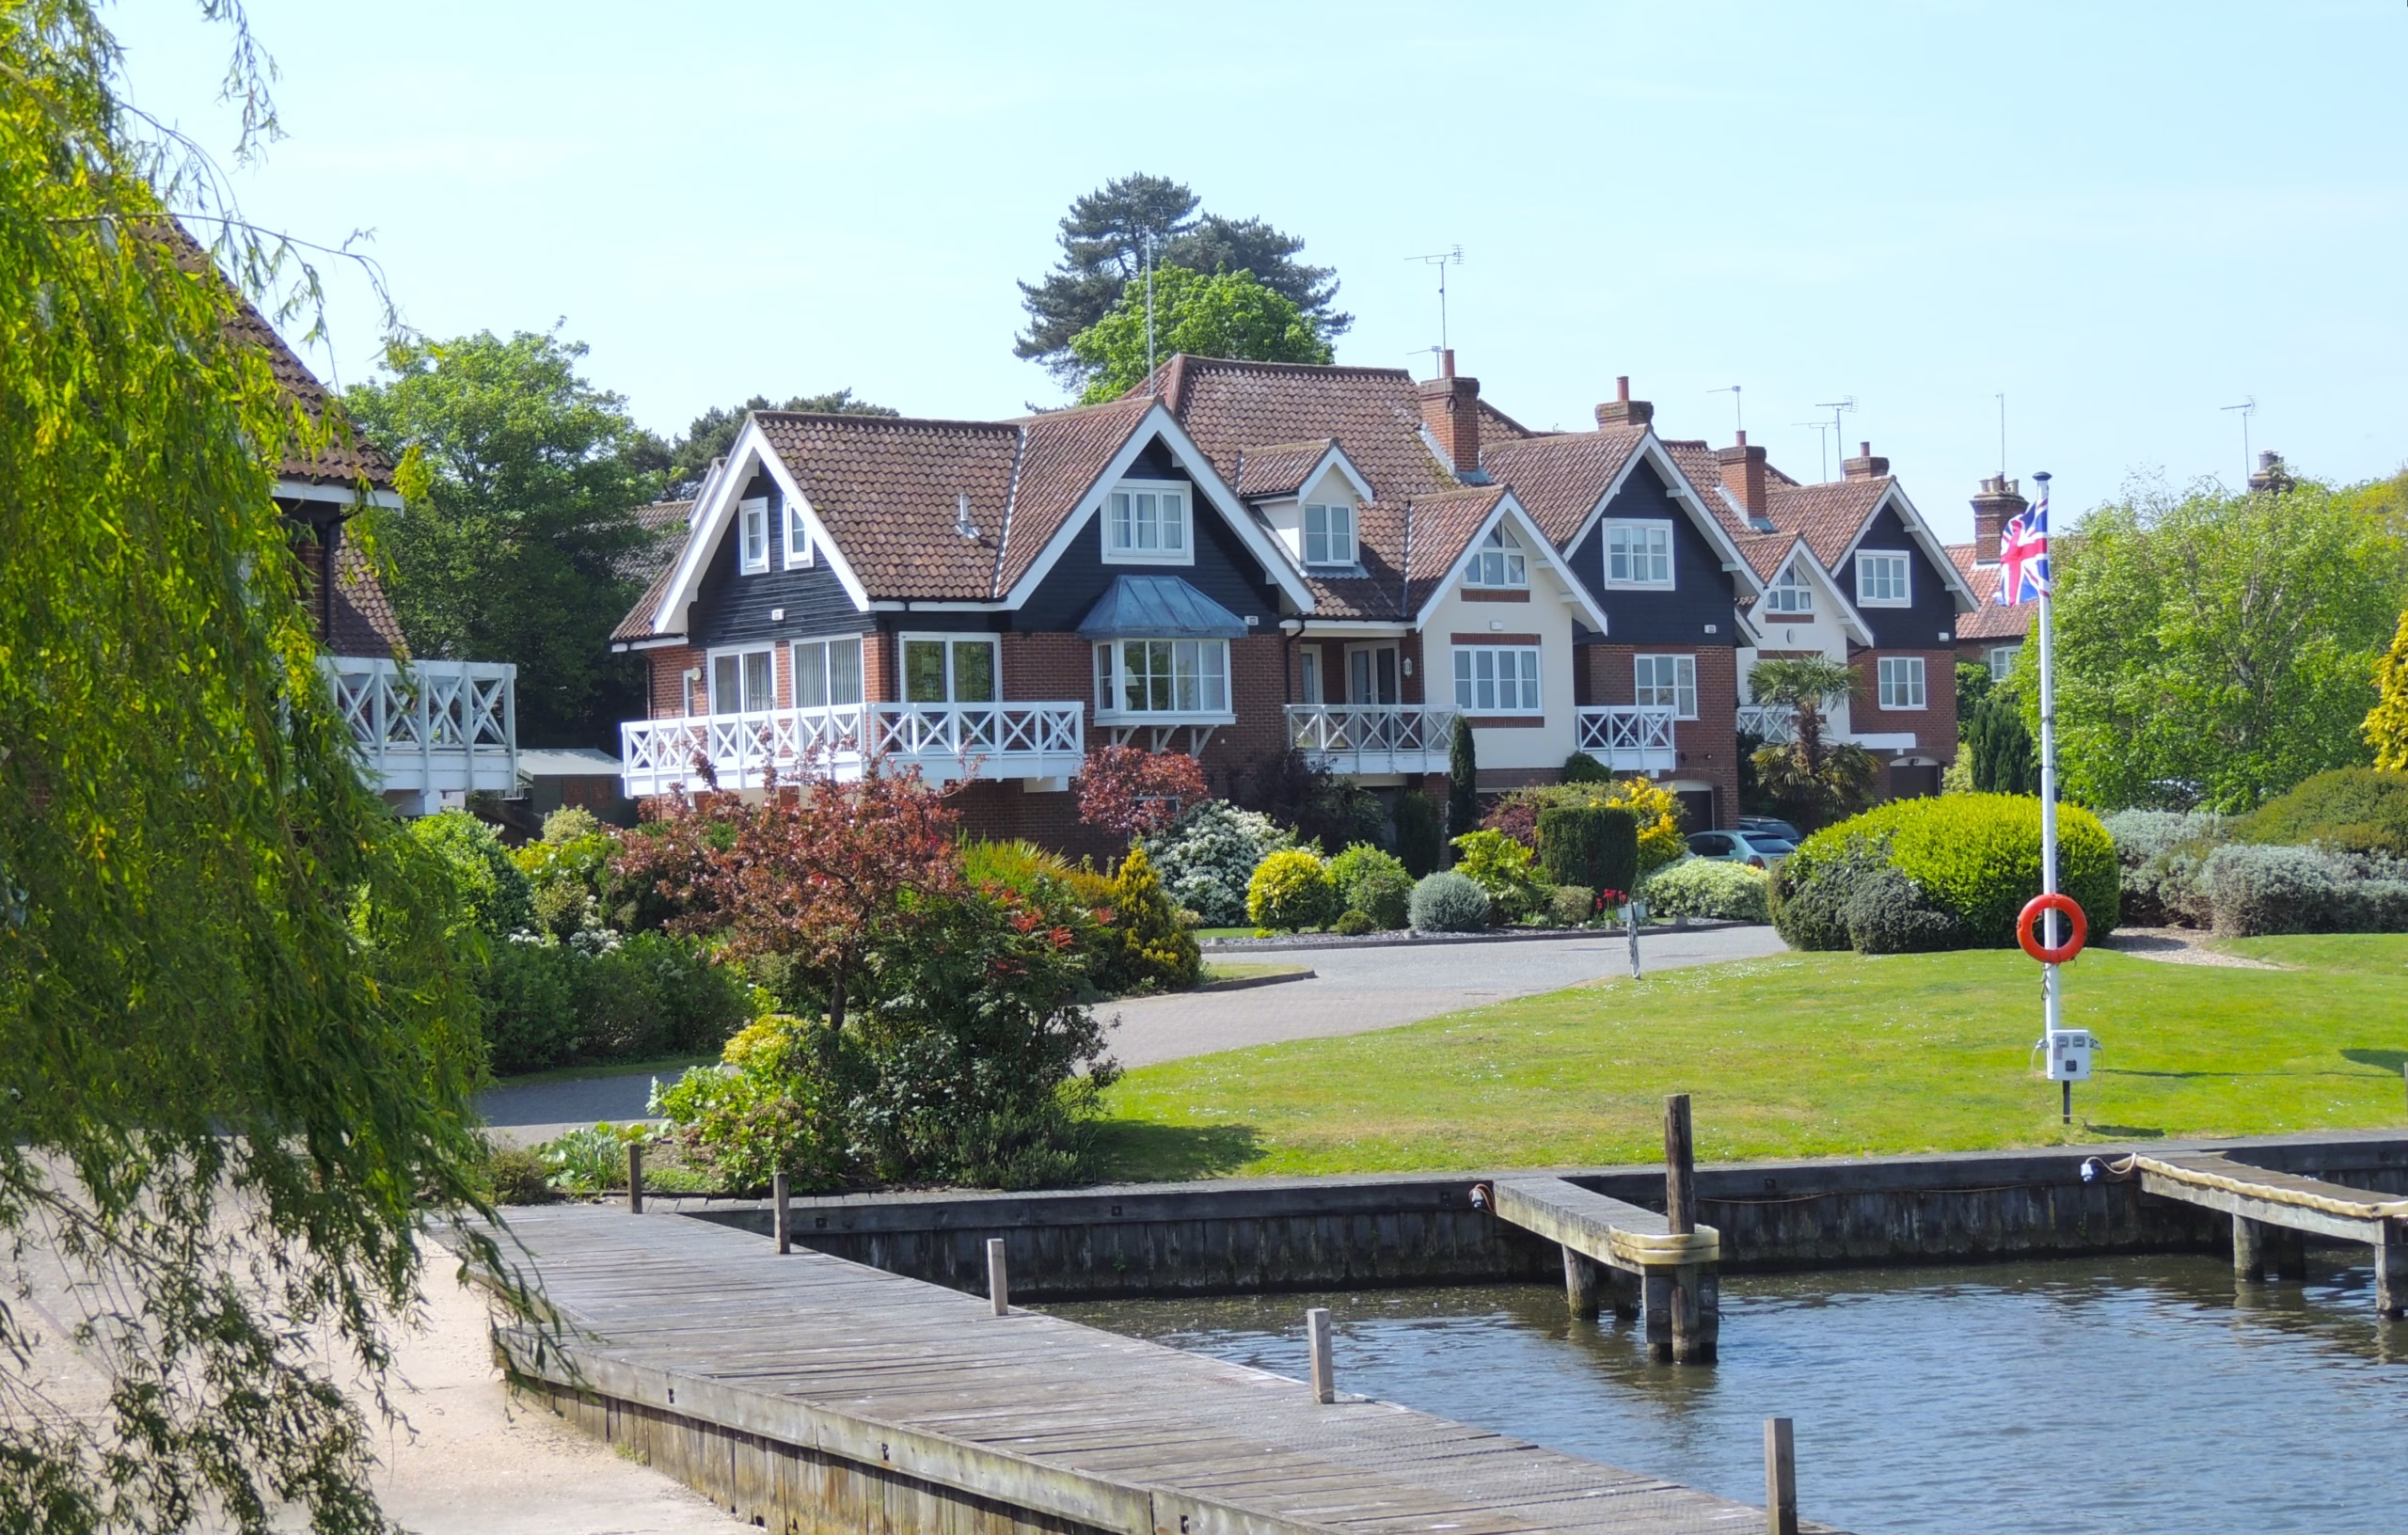
Building long-term financial security often means looking beyond traditional savings and stock market investments. For many, property can offer a tangible asset that may provide both rental income and potential long-term capital growth, although returns and property values can vary. It combines potential capital growth with passive income, making it a compelling option for future-proofing your finances.
Whether you’re an experienced investor or just starting to explore your options, understanding how property can work for you is the first step towards a more resilient financial future. This article explores the main benefits and things to consider when adding property to your investment strategy.
Diversifying Your Investment Portfolio
A fundamental principle of sound financial planning is diversification. Spreading your money across different asset classes helps reduce risk, as the performance of one asset can offset a poor performance from another. Property is an excellent tool for this because its value doesn’t typically move in sync with the stock or bond markets. Adding real estate can create a more balanced and stable portfolio.
You can diversify your portfolio with real estate in several ways, from directly owning a rental property to investing in real estate investment trusts (REITs). Each method has its own benefits and challenges. Direct ownership gives you more control but also comes with more responsibility. Understanding the pros and cons of property investment is essential before committing your money.
Property as a Stable Asset Class
Unlike shares or digital assets, property is a tangible, physical asset. You can see and touch it, which offers a sense of security that other investments can’t. Historically, while property markets experience cycles of boom and bust, they have shown a consistent upward trend over the long term. These characteristics are why some investors include property as part of a diversified long-term strategy.
This stability comes partly from the basic demand for housing. People will always need somewhere to live, which creates a constant baseline of demand that supports property values. This underlying need helps smooth out market volatility, making property a less speculative and more predictable long-term hold compared to other asset classes.
The Holiday Let Market Outlook
One specific area of the property market that has seen significant growth is the holiday let sector. The rise of the ‘staycation’ and the flexibility offered by platforms like Airbnb have created a thriving market for short-term rentals in desirable locations. For investors, this can mean significantly higher rental yields compared to traditional long-term tenancies.
Investing in a holiday home can provide both a personal getaway and a potential income stream. However, financing this type of purchase differs from a standard residential mortgage. Lenders will assess factors such as the property’s potential rental income, location, and your financial circumstances. You may therefore need a specialised holiday let mortgage, which is designed for properties intended to be rented to holidaymakers rather than used solely as a main residence. The eligibility criteria, deposit requirements, and lending terms can vary between lenders, so it’s important to understand what you’ll need before committing to a purchase.
Understanding Rental Income Potential
Before investing, it’s vital to accurately assess a property’s rental income potential. This involves more than just looking at average nightly rates in the area. You must consider factors like seasonality, local events, occupancy rates, and ongoing costs. For example, a property in a popular seaside town might generate most of its income during the summer months, while a city-centre flat may have more consistent year-round demand.
To calculate your potential net yield, subtract all operating expenses from your gross rental income. These costs include:
- Mortgage payments
- Insurance
- Council tax and utilities
- Maintenance and repairs
- Management fees if you use an agent
- Cleaning costs between guests
A realistic projection of these figures will give you a clear picture of the property’s true profitability and help you decide if it’s a sound investment.
Expert Advice for Complex Finance
Navigating the world of property investment finance can be complex, especially when dealing with non-standard assets like holiday lets or commercial buildings. The criteria for these mortgages differ significantly from those for a primary residence. Lenders have specific requirements regarding projected income, property location, and your own financial standing as an investor.
Because the market is so specialised, seeking advice from a broker who understands investment finance is highly recommended. They can access lenders and products that might not be available on the high street and can guide you through the application process. Their expertise can be invaluable in structuring a deal that aligns with your financial goals and ensures you get the most suitable terms for your investment property.
Property investment remains a powerful strategy for building wealth and securing your financial future. With careful planning and the right professional guidance, it can be a stable and profitable addition to your portfolio.